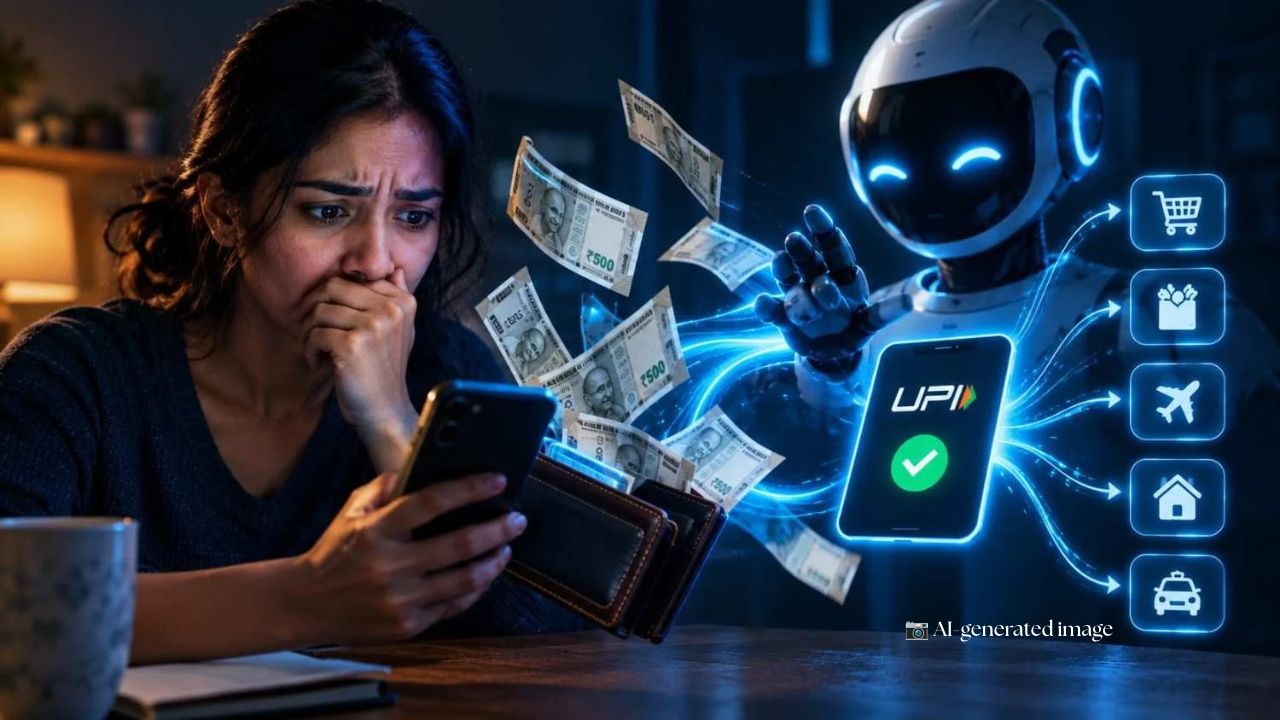
Imagine telling your AI assistant, “Order my usual groceries for the week. Keep it under ₹2,000.” You do not open Blinkit or Zepto. You do not search for every item, add products to a cart, select your address or open a UPI app to complete the payment. AI does it for you. It knows what you usually buy, checks what is available, makes the selection and places the order. It then initiates the payment within the limits you have already given it.
The groceries arrive. The money has moved. But you did not make the payment in the way you normally would. This is where the idea of agentic AI and UPI becomes more interesting than simply making digital payments faster. The technology could eventually change not only how we pay, but who makes the decisions that lead to a payment.
India is already beginning to prepare for this possibility. NPCI is working on protocols that could identify and authorise AI agents on UPI, with early use cases expected to focus on smaller, routine transactions. The wider payments industry is also looking at how AI agents can be identified, verified and given permission to act on behalf of users.
Read More | Paytm Launches Pi to Bring Agentic AI to Banks and Insurers
The question, therefore, is no longer simply whether AI can make a UPI payment. What happens when an AI can spend your money?
The payment you never actually made
Today, a digital payment follows a familiar path. You decide what you want, choose the product or service, check the amount and authorise the transaction.
In simple terms, it is: human decides → clicks → pays.
An agentic future could look very different: human gives permission → AI decides → UPI executes.
That difference is more important than it first appears. You may not tell the AI to pay a particular merchant a particular amount. You may simply give it an instruction such as, “Buy my groceries for the week and keep the spending below ₹2,000.”
Read More | GFF’26: PM Modi Calls for Next-Gen Fintech Push with AI, Tokenisation and Quantum
The AI then decides how to fulfil that instruction. This brings us to a fundamental shift in digital finance: Today, we authorise payments. Tomorrow, we may authorise decisions that lead to payments.
That could be the real change agentic AI brings to UPI.
Did you approve the payment or the AI?
Consider the difference between a regular automatic payment and an AI making a purchase. If Netflix or Jio Hotstar automatically charges your account every month, you have already agreed to that recurring payment.
But if you tell an AI, “Buy groceries for me under ₹2,000”, you have not selected every item or approved every individual transaction. You have given the AI a boundary within which it can make decisions. So what exactly have you consented to?
Did you approve the payment, or did you approve the AI’s decision to make the payment?
This question could become central to agentic finance. An AI agent may need clear permissions covering what it can buy, how much it can spend, which accounts it can access and when it must ask the user before acting. The user could remain in control, but that control may increasingly come through rules and limits rather than individual clicks.
This is also why the idea of “Know Your Agent” is beginning to emerge alongside “Know Your Customer”. SBI Chairman C.S. Setty has called for a framework that can establish an AI agent’s identity, consent, transaction limits and audit trail as these systems become more involved in financial activity.
UPI could become the layer we barely see
UPI’s success has been built around simplicity. It removed much of the friction between a bank account and a payment. Agentic AI could remove another layer: the need for the user to actively participate in every step.
Read More | UPI Turns 10: How India’s Payment Revolution Changed Everyday Life
The user could interact with an AI rather than a payment application. The AI could handle the shopping or booking process, while UPI works underneath to move the money. That creates a simple way of looking at the possible future:
Human = intention and permission
AI = decision and action
UPI = movement of money
The human says what they want and sets the boundaries. The AI works out how to achieve it. UPI handles the financial transaction.
If this model develops, UPI could become less of a payment destination and more of an underlying financial layer for AI-driven activity. The irony is that UPI’s biggest transformation may eventually be that people use it without consciously thinking about using it.
What happens when AI starts negotiating?
The grocery example is relatively straightforward. The more radical possibility comes when AI agents begin making more complex decisions. Imagine asking your AI to book a flight within a certain budget. It could compare prices, timings and baggage conditions before selecting an option that fits your instructions.
Now take that one step further. Today, an AI could potentially act as your shopping assistant. Tomorrow, a more advanced possibility is that your AI could negotiate directly with another AI representing a merchant.
Your AI knows your budget and preferences. The merchant’s AI knows its products, stock and prices. The two systems could exchange information and reach an agreement before a payment is made. The transaction could then become:
Human intention → AI decision → AI negotiation → UPI payment.
If two machines can negotiate a price and one can authorise the payment, where exactly does the human sit in that transaction? The human may still be the owner of the money and the person who sets the rules. But the actual transaction could be shaped almost entirely by machines.
The harder question: who takes responsibility?
Greater automation also brings greater responsibility. What happens if an AI misunderstands an instruction and spends more than expected? What if it selects the wrong product? What if someone gains access to the agent and uses its permissions? And what happens when the same mistake is repeated across hundreds of transactions before anyone notices?
Read More | Is a Tech War Brewing Over India’s UPI? Who Will Lose Control?
These are not problems that technology alone can solve. The future of agentic payments will require clear rules around identity, authentication, spending limits, user consent and responsibility. An AI may be capable of taking an action, but that does not automatically mean it should be allowed to take that action without safeguards.
This is why current efforts to build systems for identifying and authorising AI agents are important. NPCI is exploring how AI agents can operate within UPI, while global payment companies are also working on ways to establish trust around AI-led transactions. The technology may move quickly. Financial trust will have to move with it.
Could UPI become a financial operating layer?
This is where the idea becomes bigger than payments. If AI becomes the decision layer and UPI becomes the transaction layer underneath it, the two could together create a new way for people and businesses to interact with money.
An AI could manage routine purchases, arrange services, compare offers or handle certain business expenses. UPI could provide the mechanism for moving money once those decisions are made. The user may see only the AI. The merchant may see only the order. The bank may see the transaction.
Read More | CRED Launches AI Credit Coach to Simplify Credit Scores & Boost Financial Awareness
But underneath them could be a financial system connecting people, businesses and increasingly capable AI agents. That does not mean UPI will necessarily become a “financial operating system”. Regulation, security, consumer trust and the development of agentic AI will all determine how far this model can go.
But the possibility is worth considering because the role of UPI could change even if the underlying payment system remains largely the same.
What if the human becomes the rule-maker?
Perhaps the most significant change will be in our own role. Today, we make the decision and approve the payment. In an agentic future, we may increasingly define the rules and allow AI to operate within them.
We might tell an AI how much it can spend, which purchases require approval and which transactions it can complete automatically. Instead of authorising every action, we could authorise a system to make certain decisions for us.
Read More | Google Launches Ask Google Pay: Gemini AI Assistant to Help Users Track Spending and Save Smarter
That could make financial life easier. It could also make our relationship with money more distant. We may become less involved in individual transactions while becoming more responsible for the boundaries we give the machines making them.
That leaves the future of UPI at an interesting crossroads. The next big change in payments may not be another faster way to press “Pay”. It may be a world where the payment happens almost as a consequence of an AI decision.
UPI could remain the system that moves the money. AI could become the system that decides when, where and why that money should move.
And if humans increasingly move from approving payments to authorising the machines that make them, will we still think of a payment as something we made at all?

Indrani Priyadarshini is a journalist and editorial professional specialising in technology, artificial intelligence, smart cities, green energy, and digital transformation. With over four years of experience in tech journalism and digital media, she is known for turning complex industry developments into clear, engaging, and insightful stories. Her expertise spans reporting, editorial strategy, digital publishing workflows, and in-depth coverage of emerging technologies shaping the future.